International compliance calendar
2027 Business Compliance Deadlines
Compare 2027 invoicing and tax reporting deadlines in Germany, Spain, France and the UK, with official sources and practical preparation steps.
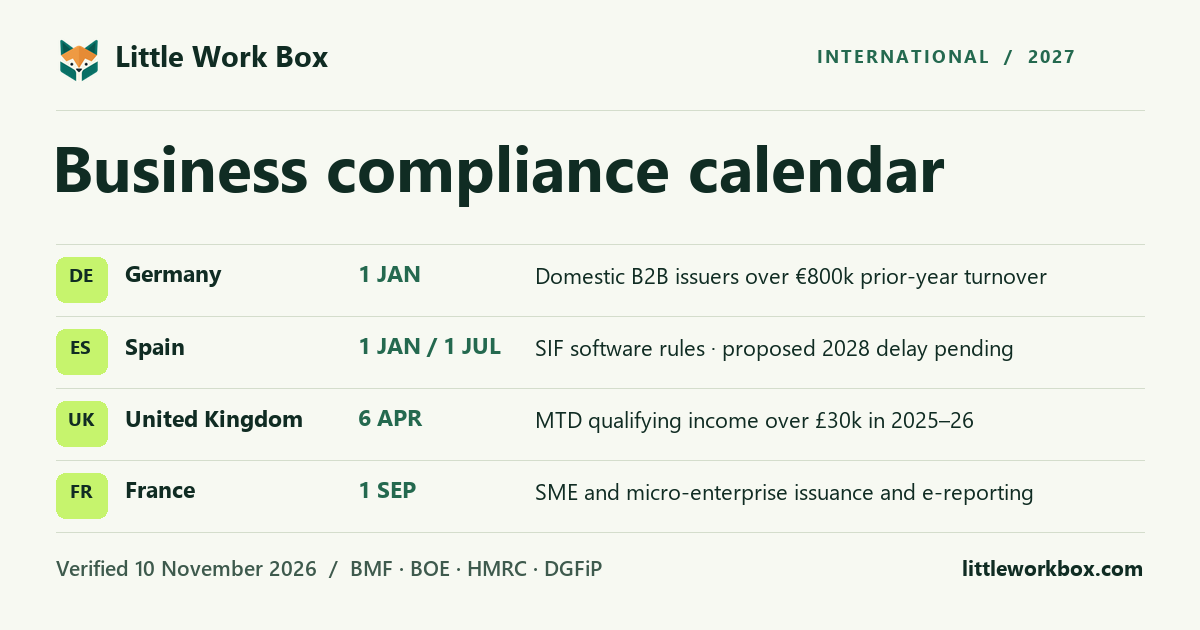
Four countries have different triggers. Germany looks at the transaction and issuer turnover, Spain at the taxpayer and invoicing system, the UK at qualifying income, and France at business size and transaction type.
Download the one-page calendar (PNG)
Germany — 1 January 2027
Domestic B2B e-invoicing. In-scope issuers with prior-year turnover over €800,000.
Check your export profile and agree on the delivery channel. Eligible smaller issuers and certain EDI arrangements can use transitional rules through 2027. The general transition ends in 2028.
Spain — 1 January and 1 July 2027
Invoicing software (SIF / VERI*FACTU). In-scope corporate income tax taxpayers in January. Other in-scope taxpayers, including many autónomos, in July.
Adapt your software before the applicable date. Hacienda has announced a proposed delay to October 2028. The consolidated BOE still lists the 2027 dates as of the review.
BOE — Royal Decree 1007/2023 · Check the size and format of a test file
UK — 6 April 2027
Making Tax Digital for Income Tax. Eligible sole traders and landlords with more than £30,000 of qualifying income in 2025–26.
Choose HMRC-compatible software, keep digital records and prepare for the first quarterly update by 7 August 2027.
HM Revenue & Customs · Check the encoding of a sample CSV export
France — 1 September 2027
Electronic invoice issuance and e-reporting. SMEs and micro-enterprises with transactions in scope. The receipt requirement started on 1 September 2026.
Connect to a registered platform. Test domestic B2B issuance and the separate reporting flow for in-scope transactions and payments.
Plan a test before each deadline
Record which entity, transaction and system each rule covers. Assign an owner, then test a real workflow with fictional data. For invoices, try an issue, rejection and correction. For UK reporting, reconcile a sample quarter against your source records.
German domestic B2B rules do not automatically cover an Austrian supplier selling to a German customer. Ask the recipient which format and channel they accept, and check the requirements for the transaction separately.